Showing posts with label online stock trading and investments. Show all posts

Wednesday, November 17, 2010

personal finance blog


This Month at Cato Unbound


This month at Cato Unbound we’re debating campaign finance regulation, with a panel of notable contributors and a big, new idea.


That idea is semi-disclosure, in which information about campaign funding is collected and disseminated, but, much like the census, personal names and addresses aren’t attached. Political scientist Bruce Cain suggests semi-disclosure might break the impasse between privacy and the right to know. Others? Well… you’ll just have to wait and see. Joining us will be Nikki Willoughby of Common Cause, election law scholar Richard Hasen of Loyola Law School, and the Cato Institute’s own John Samples. Discussion will run through the rest of the month on this vital issue to our nation’s democracy.


In response to my article on currency controls and QE feuding in many countries (See South Korea, Hong Kong, Brazil, China, Volcker Complain about Bernanke's QE Policy), reader Robert has some personal observation on happenings in Poland.

Robert writes ...

Hi Mish,

I'm a long time reader of your blog - congratulations on doing such a good work for so long!

I've just read your recent post on international reactions to QE2 and the threat of worldwide capital controls. I have something to add here from my country.

In Poland, there has been a bubble in real estate since 2006-2007 that never really popped. Condo prices in downtown Warsaw (capital of Poland) are comparable to prices in Berlin and Vienna, and of course incomes and standard of living are way way lower.

Real estate prices have fallen 10-15% from the peak alright, but incidentally our currency has recently strengthened, so the net result from the international perspective is nearly zero. Real estate prices has been fueled, as is typical for the whole region of central-eastern Europe and Baltic States, by cheap capital denominated in CHF (Swiss Francs) and EUR (earlier in the decade USD), coordinated mainly by Austrian and Italian banks and originating in Switzerland and ECB.

With this situation, there is a growing pressure, at least a year running, from our central bank and partly from the finance ministry to curb the inflow of cheap money and seemingly - although it is never openly admitted - to try and prick the real estate bubble, the bubble that has indeed reached a ridiculous size and is pushing more and more families into debt servitude.

There has been a series of banking regulations ("recommendations") issued by Komisja Nadzoru Finansowego (Commision of Financial Supervision) that targets inflows of cheap money. The curbing is effected mainly by reining in the mortgage market, that has been - again, as is typical for the whole region - the main venue of external capital inflow. Recently there have been two important regulations issued on that matter. Recommendation SII(effective January 2011) mandates that banks should have no more than 50% mortgage portfolios denominated in foreign currencies and effectively mandates (at least for the not very wealthy customers) that mortgages be issued for no more than 25 years. Recommendation T (effective September 2010) mandates that LTV for forex mortgages should never exceed 80% and that banks must consider harsh changes in the interbank market rates when qualifying customers for such loans.

It has been also recently discussed that possibly somewhere in 2011 a regulation will be passed that completely cuts people off from foreign currency mortgages unless they actually have assets (other than real estate itself) that can balance the Forex risk or Forex earnings.

Such regulation would effectively almost totally cut off cheap external mortgage financing.

There has also recently been a change in language of Polish banking regulators. It is now quite openly said that the practice of selling very long term, adjustable rate mortgages denominated in foreign currency should be literally "brutally and completely curbed" (words of the chairman of NBP, our central bank).

This is a process that is slowly but regularly unfolding and will surely take some more time; cheap EUR mortgages are still widely available and will be at least until the end of 2010. But it seems that the process of curbing capital inflows is gaining pace rapidly in Poland and it should bear very concrete fruits in 2011 and 2012,
especially taking into account recent acceleration in Fed lunacy that could (and I expect it will) spur counter reactions in my country analogous to what is happening in Korea or Brazil. There are no reactions as of yet, but I expect them soon.

It should perhaps be added that Polish banking regulator bodies and central bank are quite independent from the government and it seems that this independence is factual, not merely statutory; there have been many episodes in the last decade that NBP was in harsh conflict with the govt.

greets,

Robert
Poland Stats: 62% of Mortgages, 23.9% of Corporate Loans made in Foreign Currencies

In a followup question I asked Robert what percentage of mortgages in Poland were in foreign currencies. Here is Robert's response ...
Hello Mish

This is straight from the central bank's data: 158203.4 M PLN foreign currency (56.64 billion USD, 62.03% total), 96837.7 M PLN domestic currency (34.67 billion USD, 37.97% total). All USD values calculated according to current Forex ask rate.

That was household mortgages. On the other hand, statistics of corporate credit show the exactly opposite behavior: 157110.5 M PLN domestic currency (56.25 billion USD, 76.1% total), 49335.7 M PLN foreign currency (17.66 billion USD, 23.9% total).

Forex corporate credit is quite steadily declining (in nominal terms) since february 2009, as well as domestic currency corporate credit. What is perhaps more alarming (especially that real estate prices are slowly but steadily declining) is that household mortgage credit is relentlessly growing as if no financial crisis occurred at all and the good times roll; domestic currency mortgages are up 29.3% nominally yoy, foreign currency mortgages up 12.3%.

The recent deceleration in growth of Forex household mortgages and acceleration in domestic currency mortgages is attributable entirely to a special government financial program ("Rodzina na Swoim", "Family on its own") that lets you get a domestic currency mortgage with extra payment from government that amounts to 0.25-0.5 of interest paid, so effectively the interest on such mortgages for the final customer is 0.5-0.75 of "normal" market rate; that might finally amount to 2.7-4% - such rates are comparable to what one can get for forex mortgages (in spite of rates in Poland being in theory a healthy 2.5-3.5 percentage points above Switzerland, ECB or USA), so it is understandable that there is a lot of demand for domestic currency mortgages currently.

What should be stressed is that this special payment program is phased out in 2011 (our government has recently a very hard time explaining to the public opinion and independent economists why the deficit and debt grows so quickly; there are indeed many austerity pressures); as of January 2011 it will be offered only to people buying new development real estate and some time in 2011 H2 (don't remember exactly when) the program expires entirely.

It is widely and correctly expected that if this happens and the supply of foreign currency credit is not curbed, people will again widely take on mainly EUR, and to a lesser amount CHF and USD denominated mortgages. This scenario is apparently explicitly targeted by the banking regulators, as I wrote in the earlier mail.

It should be added that nearly all mortgages in Poland are ARMs with interest invariably calculated as WIBOR (polish interbank market rate)+margin or LIBOR/EURIBOR+margin. The margin typically is, depending on LTV and customer's creditworthiness (which actually IS checked quite thoroughly), 1.1-2 percentage points for PLN and EUR mortgages and 2-3.5 percentage points for CHF and USD mortgages.

3-month WIBOR (interbank rate for PLN deposits) is currently at 3.85%, the yield curve is normal and not very steep (both for interbank rates and govt bonds). Polish central bank, as most central banks do currently, targets short term rates which is understandable from their viewpoint as it allows almost full control over both commercial credit and mortgage rates - as I said earlier, almost all mortgages are ARMs indexed to short-term interbank rates. Interest rate swaps for foreign currencies are nearly unavailable to "mere mortals" in Poland and domestic currency IRSes are simply non-existent (no demand I guess, everyone is happy with plain ARMs).

Wow, I just described like a half of Polish financial market. Cheers,

Robert
Thanks Robert! I always appreciate emails like yours so readers in the US can find out what is really happening in Europe.

Mortgages denominated in foreign currencies are a disaster waiting to happen, not only for the debtors but to the banks that made the loans.

Mike "Mish" Shedlock
http://globaleconomicanalysis.blogspot.com
Click Here To Scroll Thru My Recent Post List


alpine payment systems scam

Small Business <b>News</b>: Entrepreneurs and The Economy

Entrepreneurs and small businesses are important to economic recovery. This we hear on the news regularly. But it is also important that entrepreneurial efforts.

BillBoard - Blogs - The Buffalo <b>News</b>

The Buffalo News updated every day with news from Buffalo, New York. Links to national and business news, entertainment listings, recipes, sports teams, classified ads, death notices.

Good <b>news</b>: Feds to ban caffeinated alcoholic drinks for some <b>...</b>

Good news: Feds to ban caffeinated alcoholic drinks for some reason.


A Specialized Meat Shop at the St lawrence Market by adawnjournal


Small Business <b>News</b>: Entrepreneurs and The Economy

Entrepreneurs and small businesses are important to economic recovery. This we hear on the news regularly. But it is also important that entrepreneurial efforts.

BillBoard - Blogs - The Buffalo <b>News</b>

The Buffalo News updated every day with news from Buffalo, New York. Links to national and business news, entertainment listings, recipes, sports teams, classified ads, death notices.

Good <b>news</b>: Feds to ban caffeinated alcoholic drinks for some <b>...</b>

Good news: Feds to ban caffeinated alcoholic drinks for some reason.


alpine payment systems scam

Small Business <b>News</b>: Entrepreneurs and The Economy

Entrepreneurs and small businesses are important to economic recovery. This we hear on the news regularly. But it is also important that entrepreneurial efforts.

BillBoard - Blogs - The Buffalo <b>News</b>

The Buffalo News updated every day with news from Buffalo, New York. Links to national and business news, entertainment listings, recipes, sports teams, classified ads, death notices.

Good <b>news</b>: Feds to ban caffeinated alcoholic drinks for some <b>...</b>

Good news: Feds to ban caffeinated alcoholic drinks for some reason.

Friday, September 24, 2010

managing your personal finance


A lot of people are unemployed in this country, 14.9 million as of the latest BLS release a couple of days ago, and for some of those people, this has become what is coyly referred to as ‘the entrepreneurial moment’, the ‘ah-ha’ light-bulb realization that if they don’t create a job for themselves, there will be no job, no income, no mortgage payment, no groceries, no light, no heat, no gas for the car, nuthin’. Since 2008, over 5 million jobs have been lost, many of which will never, ever come back.


Welcome to Labor Day, 2010.


Some of these ‘lost’ jobs have been outsourced overseas. Some have just been cut. Some companies are using their cash to invest in technologies which will insure that they will never have to hire these folks back, at least not with the skills that they had when they were given a cardboard box and five minutes to empty their desks and get out the front door.


If there are people out there who have or are considering building their own ‘life raft’ it would surprise absolutely no one; though for some folks, entrepreneurship is so scary, they can’t imagine anything other than hiring on to someone else’s deal, no matter how horrible it is.


Sometimes, though, you don’t have any choice. One thing to remember, is that many of the most successful entrepreneurs in this country have not invented fuel cells, high tech photovoltaic films, high speed transit, a cure for cancer (or the common cold), or the answer for peace in our time. They are cleaning houses, making pizza, fixing computers/ipods/iphones/cars/furnaces/plumbing/household electric, managing other people’s systems, giving advice, making clothing for people who are outside the common size ranges in the stores.


Not exactly operating a basement boiler room financial situation, doing crazy financial stuff, or stirring up the pot on international finance.


At its most basic, it’s local; at its most interesting, it might even be regional. But it is still person to person; it’s still me doing business with you. Face to face. My hands and brain doing stuff to help you. Some of this is amazingly low tech – some of it is almost medieval.


This week’s fascinating story comes from the New York Times about a family of knife sharpeners who have thrown a new curve on this ancient of trades by providing two sets of knives to butchers, restaurants, food services (in Yankee Stadium, for heaven’s sake), and calling on a weekly basis to pick up the used set and providing the newly sharpened set.


Anyone who does any real work in a kitchen at all knows that your most important tools are a good set of knives and a good frying and sauce pan. With those three things, you can do almost anything (and yes, I have made cookies in the bottom of a frying pan; thank you for asking), but if your knives are dull, cutting anything becomes horrible work and you can injure yourself badly. “Every week, the company visits more than 800 clients and collects more than 8,000 knives to be replaced with freshly sharpened blades. The service costs $2.50 to $3.50 per knife.


The business started servicing mainly butchers and meatpackers, in territories handed down from father to son. To preserve the business for his children, Mr. Ambrosi expanded it to restaurants and even Yankee Stadium, in some cases deviating from long-held tradition. Many cooks and chefs take personal pride in their knives and their ability to maintain them, and would hesitate to release them to anyone else’s care. But sharpening a knife takes time and skill — and not every chef has both.”


Having a skill and honing (sorry) that so that you can provide something that someone else can not (or will not) do, whether it is being an electrician, a plumber, a welder, a knife sharpener, a shoe repair shop, a hair dresser, whatever it is – can make the difference in today’s international economy between being able to make a living for your family and holding your head in your hands. One of America’s biggest mistakes as far as education is concerned (and others might just argue with me) is that we “jumped the shark” in terms of absorbing people coming out of colleges.


Since the 1980s, kids coming out of college have had fewer and lower level opportunities. Jobs which absorbed high schoolers, now require a 2 or 4 year degree; job that required a college degree started to require a masters degree; some jobs which required a college degree and some internal training, now require advanced degrees – I even know of jobs that now require a legal degree to be hired which 30 years ago required a college degree and passing a test. So much emphasis was placed on going to college – and vocational training and the trades were so downgraded and derided that any family with a kid with two brain cells to rub together would not even THINK of encouraging that kid to go into the trades, unless the family was already in the business.


We’re now at a situation where companies, which shot themselves in the foot by sending skilled jobs overseas and now want to bring them back because costs overseas have risen and/or they are tired of their intellectual property being stolen and sold to others, can’t find the skills they want. Not to put too fine a point on this – those same companies have not done any training themselves; nor are they willing to do so. They got into the habit a long time ago of pushing the investment in training off on others. The government for one.


The other, which has willingly and consistently provided training in the trades for years are the unions. Organized labor. The Great Satan of the industrial world. The guys everyone loves to hate. The organizations which, according to many employers, stand in their way of succeeding in business.


But still, the organization which has kept skills alive in this country despite outsourcing, overseas sourcing, attacks from business and government, and general antipathy from great swaths of the American population in certain parts of the country.


So. On this frankly very sad Labor Day, 2010, I’d like to thank the American Labor Movement for remembering what America and Americans do best and what we need to do on an increasing basis if we are to put people back to work – or if we are to have businesses to call our own: Do stuff with our hands.


Thanks folks. You’re not perfection, but you’re willing to invest in Americans.


Happy Labor Day


  • CEDIA: LG, JVC and Sony debut LCoS-based 3D front projectors


  • BMW ActiveE electric car - Consumer field trials to begin next summer


  • Five insider shopping tips for Gordon Gekko


  • Daily Dispatch: Google NEW lists updates of all its products; Survey reveals people prefer colonoscopies to computer maintenance


  • 2010 Distracted Driving Summit: What’s next for combating driver distractions?


  • What's the deal with car tire pricing?


  • Q&A: Short on salt


  • Daily electronics deals


  • 6 painless ways to cut your grocery bill


  • Go green for school supplies


wps big white booty

Scripting <b>News</b>: Angelgate in a Nutshell

Recent stories. Twitter links. My 40 most-recent Twitter links, ranked by number of clicks. My bike. People are always asking about my bike. A picture named bikesmall.jpg. Here's a picture. AFP news pic. Calendar ...

Arab move to censure Israel stymied at UN meeting | Updated <b>News</b>

LATEST NEWS � Plane off runway in Sicily, 20 slightly injured � Arab move to censure Israel stymied at UN meeting � Small-town mayors targeted by Mexican drug gangs � Fla. bank robbers strap bomb to abducted teller � Belgian skydiver on ...

<b>News</b> - Lindsay Lohan &quot;Demure and Quiet&quot; as She Arrived at Jail <b>...</b>

Like her previous stints in the slammer, she'll be kept away from other inmates in a 12x9 cell.


big white booty

Scripting <b>News</b>: Angelgate in a Nutshell

Recent stories. Twitter links. My 40 most-recent Twitter links, ranked by number of clicks. My bike. People are always asking about my bike. A picture named bikesmall.jpg. Here's a picture. AFP news pic. Calendar ...

Arab move to censure Israel stymied at UN meeting | Updated <b>News</b>

LATEST NEWS � Plane off runway in Sicily, 20 slightly injured � Arab move to censure Israel stymied at UN meeting � Small-town mayors targeted by Mexican drug gangs � Fla. bank robbers strap bomb to abducted teller � Belgian skydiver on ...

<b>News</b> - Lindsay Lohan &quot;Demure and Quiet&quot; as She Arrived at Jail <b>...</b>

Like her previous stints in the slammer, she'll be kept away from other inmates in a 12x9 cell.


G20 Summit, London, G20 London, G20 Protests, G20 Demonstrations by G20London2009


G20 Summit, London, G20 London, G20 Protests, G20 Demonstrations by G20London2009


personal finance budgets


It's hard to beat an excel spreadsheet for quickly shifting between a granular and top-level view of your personal finance situation. Here's reader Lauren's account balance spreadsheet she made to keep track of her expenditures, past, present, and future, and itemize her budget.


Download Lauren's Budgeter (XLS)


1. Scroll to the current month.

2. Enter your current balance in the "Starting Balance" box at the top left.

3. Enter your credits and debits on the appropriate dates they will hit your account. Use positive numbers for money getting added credits, and negative numbers for when it's getting taken away.

4. The green "Total" will change to reflect your total overall balance.


Use it as is, compare it to your own, or mod to fit your own needs.


Lauren says it's "quite nifty," and also uses it as a calendar.


Here's the excel code for the totaler for those who like to look under the hood:


TODAY();_8_10)

+SUMIF(_9_10d;"
If you walked into the average bookstore, you'd think that women rule the roost when it comes to personal finance. From Suze Orman's now-classic Women and Money to the more recent (and more colorfully titled) Bitches on a Budget, there's no shortage of do-it-yourself financial advice tailored to women.


Apparently, though, when women make the momentous move from self-help to seeking professional advice about investing and retirement, things go rapidly downhill. A recent study by the Boston Consulting Group revealed that women perceived themselves as receiving wealth management services at a level of quality that is inferior to that received by their male counterparts.


According to the study, women are the key decision-makers when it comes to 27% of the wealth worldwide: that's $20 trillion! But despite the massive chunk of power they wield, 55% of the women surveyed in the study said they felt their wealth manager could do a better job of advising them. Almost a quarter of the respondents said private banks needed "significant improvement" in the services they offer to women.


"The dissatisfaction stems from the unshakable perception that men get more attention, better advice, and sometimes even better terms and deals," according to study co-author Peter Damisch. "We heard this sense of subordination time and time again in our interviews."


This perceived disparity in service arose from several key disconnects in the relationships and communications between women and their financial advisers. Manisha Thakor, Chartered Financial Analyst and women's financial literacy advocate, offers some steps savvy female investors can take to avoid being under-served by their wealth managers and investment advisers:


1. Find your adviser and get your financial education from women-run resources.


The financial services industry is dominated by males and therefore the "DNA is structured around the male experience," Thakor explains, adding that she sees many firms making an effort to change this. Most financial advisers are men, who may not inherently understand the whole-life nature of the average woman's financial plans and needs. They also may have very different communication styles than their women clients.


Thakor recommends women use women-created resources like LearnVest and DailyWorth to educate themselves in order to avoid the intimidation factor when talking about investment products with their advisers. She also encourages women to consult Garrett Planning Network, founded by Certified Financial Planner Sheryl Garrett, to locate a local certified financial planner who works on an hourly-fee-only basis. Taking these steps, Thakor explains, may alleviate the concern expressed by many women in the BCG study that they were not being taken seriously or talked to on the same level as male clients by their financial advisers.


2. Expressly state your ideal career trajectory, then ask how you should alter your investment plans accordingly.


In the BCG study, women stated that their investment advisers fundamentally misunderstood what was actually important to them, and recommended a too-narrow range of inappropriate investment vehicles as a result. Many said their advisers assumed they had a lower risk tolerance than they actually did, or that their advisers focused on short-term results and disregarded their long-term goals, which often included time out to care for a child or parent.


Thakor offers women a script of sorts to remedy this communication disconnect. "Go in and say: "I want to be a mom and I may take X amount of time out of the work force," she advises. Then ask, "How do we adjust how much I need to save and how I should invest to compensate for this?"


3. Start saving early.


big white booty companies

Artnet <b>News</b>: Gang assaults Turkish galleries. Plus, Miami <b>...</b>

ARTNET NEWS. Gang assaults Turkish galleries. Plus, Miami Sculpture Biennial, Prospect 1.5 New Orleans, more.

Bad <b>news</b> for green technology | Watts Up With That?

Super magnet production has also been shipped over to China http://www.chinamagnet.in/i-News-229212/The-development-and-applications-of-Rare-Earth-Permanent-Magnetic-Materials-244616.html. Over the last 10 to 20 years companies have ...

&#39;Fox <b>News</b> Sunday&#39; to Host Kentucky Senate Debate - NYTimes.com

Jack Conway, Kentucky's attorney general and the Democratic candidate for Senate, and Rand Paul, the Republican nominee, have agreed to a live debate on "Fox News Sunday" on Oct. 3.


big white booty

Artnet <b>News</b>: Gang assaults Turkish galleries. Plus, Miami <b>...</b>

ARTNET NEWS. Gang assaults Turkish galleries. Plus, Miami Sculpture Biennial, Prospect 1.5 New Orleans, more.

Bad <b>news</b> for green technology | Watts Up With That?

Super magnet production has also been shipped over to China http://www.chinamagnet.in/i-News-229212/The-development-and-applications-of-Rare-Earth-Permanent-Magnetic-Materials-244616.html. Over the last 10 to 20 years companies have ...

&#39;Fox <b>News</b> Sunday&#39; to Host Kentucky Senate Debate - NYTimes.com

Jack Conway, Kentucky's attorney general and the Democratic candidate for Senate, and Rand Paul, the Republican nominee, have agreed to a live debate on "Fox News Sunday" on Oct. 3.


What are loans? by eric731


What are loans? by eric731


Saturday, September 18, 2010

personal finance planning


I've read a lot of stores lately about "credit score enthusiasts" who want to get the perfect credit score or are obsessed with improving their score. While it's certainly better than not caring about your credit score at all, it almost never pays to get a perfect score.


Despite all the stories about the odd ways your score is being used, the reality is that once you have a good credit score, you don't need to obsess about it.


Consider this - if your score is better than 760, then Fair Isaac Corporation, the company that invested the credit score formula; says you get zero benefit from improving it. For mortgage interest rate purposes, a 761 is the same as an 850. For auto loans, the bar is even lower. If you have a score about 720, it's the same as having a perfect score of 850. Visit their site and look in the right hand column - there's a table listing FICO scores and APRs for 30-year fixed mortgages, 15-year fixed mortgages, and 36-month auto loans.


If you are planning on getting a loan in the next year or two and your score is close to the next tier, by all means try to improve it. If you aren't planning on getting a loan and you have a decent score, focus your energies on something else. I assure you that you will get a better return doing something other than obsessing about your credit score.


Jim writes about personal finance at Bargaineering.com.


eric seiger dermatologist how to lose weight fast penis extender

Would You Pay for Online <b>News</b> Content? « Internet Nut

It cannot be denied that newspaper circulation and the rate of real media advertising is on the decline. As more and more people turn to modern technology and.

Small Business <b>News</b>: Small Biz Bill Passed

So what do you think of the new small business bill passed recently in the US Senate? Supporters are no doubt high-fiving each other and congratulating.

The Hockey <b>News</b>: Edward Fraser&#39;s blog: THN.com Blog: Flyers “way <b>...</b>

Philadelphia's senior vice president explains why this year's team will be even tougher and why their goaltending situation is where they want it to be.


 by Julia Delligatti


Tuesday, September 14, 2010

personal finance and budgeting


BillFloat Pays Your Bills When You Can't


If money's tight and you need a little extra time to cover a bill, service BillFloat can take care of it for you and you can pay them back later.

After entering the company you need to pay, you give BillFloat the amount of the bill and your account number. It'll let you know how many days it'll float the bill (a maximum of 30) and how much you'll owe BillFloat—which is generally $5, but decreases with the number of bills you pay. BillFloat will collect a little more information about you, like how you're going to pay them back, and then you'll be all set. Just make sure you'll have the money in a month, since BillFloat won't float its own bills.


  • Average gas prices--September 13, 2010


  • You voted: letter grades edge ahead in fuel economy poll


  • For rent: 4.5 billion-year-old ball of fire


  • What Obama's transportation proposals mean for travelers


  • TomTom provides update for XL 350, XXL 550, and XL 335 GPS devices


  • Cash for appliances: Rebates aplenty in states big and small


  • Apple curtails its free case program for the iPhone 4


  • Daily Dispatch: Death of the RSS reader?; Toronto produces entertaining video to promote e-waste recycling


  • September could be Home Star’s month—or not


  • LG's 60PX950, the first THX 3D plasma, headed to the CR Test labs!


penis extender

Small Business <b>News</b>: Facebook Phenomenon

The Facebook phenomenon may be the most important to small businesses on the Web currently, even if other tools like Twitter are sometimes more talked about.

Twitter To Look More Like Facebook&#39;s <b>News</b> Feed

We're trying not to be the type of people who hate change just because it's change.

New Children&#39;s Book Coming from President Obama - Political Punch

As part of the book deal then-Sen. Barack Obama, D-Ill., inked in 2004, Random House today announced the publication of a children's book by the president, “Of Thee I Sing: A Letter to My Daughters.” Political Punch Blog.


Housing Affordability Index, NAR-Home Sales by QuizzleTown


internet marketing course

Small Business <b>News</b>: Facebook Phenomenon

The Facebook phenomenon may be the most important to small businesses on the Web currently, even if other tools like Twitter are sometimes more talked about.

Twitter To Look More Like Facebook&#39;s <b>News</b> Feed

We're trying not to be the type of people who hate change just because it's change.

New Children&#39;s Book Coming from President Obama - Political Punch

As part of the book deal then-Sen. Barack Obama, D-Ill., inked in 2004, Random House today announced the publication of a children's book by the president, “Of Thee I Sing: A Letter to My Daughters.” Political Punch Blog.


big white booty

Housing Affordability Index, NAR-Home Sales by QuizzleTown


Thursday, September 2, 2010

budgeting personal finances


I’ve recently moved to an area where it is common for the small businesses not to take a card, I’m sure for this reason. I’m from a larger city where I hadn’t experienced this, so I was surprised to walk into several stores, and have to walk right back out, because I don’t have cash on me. While I understand the reasoning explained here, the business has to understand that NOT taking a card is a business risk they have to weigh. In this day’s society, most people don’t carry cash. Small businesses are closing left and right, because they didn’t plan properly for the costs of business. I expect the lights to be on when I walk in the door; do I have to pay a portion of their electricity bill too?


My husband and I simply won’t patron these places, because we don’t carry cash. I have a credit card, and pay it off at the end of each month. It is simply more convenient (and safer, as a very unlucky someone who has had her wallet stolen THREE different times) to carry plastic. [Side note: even if I didn't use the card responsibly, the credit card companies are another business, they make their profit off of people who don't have money, and want to borrow some, similar to a car rental, and if the person who uses the card, with the knowledge of their interest rate, that is their right and their concern what they do with their money, not mine.] Unfortunately, this is just part of the cost of doing business, the small purchases with the large. But as a business, that is certainly within rights to not accept a charge card. It’s just our right to go somewhere else that makes the experience convenient for the CUSTOMER, instead of the business.


As for advice for small businesses to set themselves apart, I’ll relate a short story. There is a small deli, family-owned, right across from my former workplace. Their food was good, but nothing special. Their prices were good, but I certainly could have gotten larger portions and possibly tastier food elsewhere? So why did I keep coming back? They offered something that no Subway does — when I came in, they greeted me by name, knew what I liked and suggested things, asked about my life. In the depths of the worst of the bad economy, they opened a second location across the street, because they had too much business. It’s not the economy closing the small businesses. A small business is rarely going to be able to compete in prices or convenience. So what else is there to do? Offer something I couldn’t get elsewhere–an experience.


  • Daily Dispatch: Navteq works to humanize GPS directions; Skyfire: flash capable iPhone browser submitted to Apple for approval


  • Q&A: Are liquid calcium supplements better?


  • Daily electronics deals


  • Labor Day deals without the legwork


  • Recycle your old rechargeable batteries


  • Apple revamped iPods, iTunes, and more


  • Bad eggs: 10 ways to cut your salmonella risk


  • New Whirlpool plant cooks up some jobs in Tennessee


  • Hurricane Earl: Keep yourself and your food safe


  • Should you buy an all-new car or a proven carry-over car?


pennis city

How Insiders Game User-Generated <b>News</b> for Money

I had previously believed that the world of user-generated news sites were run on a open, crowd-sourced model. You submitted news to a website like Digg and if it was interesting content with a great headline and newsworthy text it ...

A roundup of today&#39;s Apple <b>news</b>

Why has none of these so called "news" sites addressed this question? What's going to happen with all of the Apple TV's in our homes now? I would expect we see an OS update when the new version is released or sooner. 2 stars ↓↑report ...

Stabroek <b>News</b> - Retirement plans caught up in Clico (Guyana) upheaval

Perhaps Stabroek News can shed some light on this issue for me. Was CLICO owned and controlled by the Government of Guyana? Was CLICO insured by the government of Guyana? Did the government of Guyana cause CLICO to fail? ...


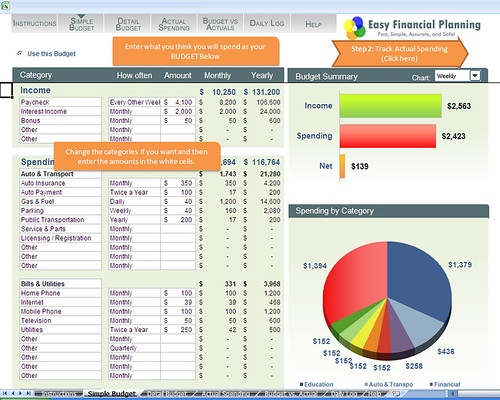
EasyFinancialPlanning.net Simple Budget by EasyFinancialPlanning.net


Wednesday, September 1, 2010

personal financeonline personal finance


lxukwiv

BBC Sharing <b>News</b> Videos With Russia&#39;s GZT.ru | paidContent:UK

The BBC has signed a deal to syndicate news video to the website of Moscow newspaper Gazeta. The arrangement will mean videos from BBCRussian.com appearing on GZT.ru, together with BBCRussian.com branding. BBCRussian.com is a service of ...

Small Business <b>News</b>: Resources For Rebirth

No matter how bleak the economic outlook, here at Small Business Trends we've always believed in the power of small business and entrepreneurship to change the.

Mark Hurd Stepping Down from <b>News</b> Corp. Board - DailyFinance

The fallout continues for Mark Hurd. The former Hewlett-Packard CEO is stepping down from News Corp.'s board of directors.


Wednesday, August 25, 2010

managing your personal finances


canadian penis extender

Health 2.0 <b>News</b>: From Space Food to Eye Tracking and Hospital <b>...</b>

Comments». 1. Health 2.0 News: From Space Food to Eye Tracking and Hospital … | Scott Ashjian News - August 25, 2010. the original here: Health 2.0 News: From Space Food to Eye Tracking and Hospital … Comments ...

Apple In Talks With <b>News</b> Corp, CBS, And Disney For 99-Cent TV Show <b>...</b>

News Corporation (News Corp) is the world's second-largest media conglomerate (behind The Walt Disney Company) as of 2008 and the world's third largest in entertainment as of 2009. The company's Chairman, Chief Executive. ...

Social <b>news</b>-reader Summify raises funds to solve information <b>...</b>

The two founders, former Google and Microsoft engineering interns, developed an algorithm that aggregates all the news from your Google Reader and Twitter accounts, eliminates the duplicates, and filters the most important news using ...


Friday, August 6, 2010

manage personal finances

Large animal medicine takes a different tack. These animals are used for industry -- food production, breeding farms, racing, and so on. (The lines are blurred in some cases, such as horses that are really pets, and greyhounds used for racing.) "The client" here is the manager, producer, or trainer, while the "patient" is the dairy herd, the swine operation, or the overall breeding potential of a winning stallion. While humane treatment is an important factor, the goals are maximizing performance, productivity, and profit. Large animal medicine focuses on designing a Herd Health Program, where the outcome of an individual case takes a backseat to the cost and benefit for the overall group.

LearnVest founder and CEO Alexa von Tobel turned down Harvard and a life on Wall Street to make personal finance education accessible to women, and she has no intention of failing.


She thinks learning how to manage your money should be simpler, a passionate belief which comes from her personal need for her New York-based company’s product, a series of online tutorials on personal finance which have led some to dub her “Suze Orman 2.0.” On Tuesday, LearnVest announced the launch of three new on-demand, online Bootcamps covering basic personal finance, cutting costs, and investing. These products are just the latest iteration in von Tobel’s quest.


The 26-year-old von Tobel got the idea for LearnVest while working at Morgan Stanley, realizing that she had no idea how to manage her own finances.


“Here I was responsible for millions and millions of dollars and I didn’t know the first thing about getting a credit card or insurance,” von Tobel said. “I needed tools like these.”


Instead of attending Harvard Business School, von Tobel put all the money she’d earned after college into building LearnVest. Since then, the company has raised over $5.5 million in financing, most recently closing a $4.5 million round led by Accel Partners in April.


The LearnVest  CEO has been spending a great deal of time in the media spotlight recently. She was recently named to Inc.’s 30 Under 30 list of young entrepreneurs and has received media coverage from a number of local and national outlets including BusinessWeek and the New York Times. The ‘Suze Orman 2.0’ moniker first came from a Fox reporter.


But behind the media attention that even has the attractive blonde’s coworkers teasingly calling her ‘Finance Barbie’ is an entrepreneur possessed. Her self-deprecating humor and amiable demeanor are genuine, but von Tobel is shrewedly packaging herself and LearnVest as an accessible and fun medium for learning about personal finance. And she’s doing it from a cubicle alongside her employees in Learnvest’s cozy New York office.


Usage statistics suggest it’s beginning to work, with Learnvest receiving about 360,000 unique visitors in the U.S. per month according to Quantcast, a Web-traffic-measurement service..


While von Tobel is certainly passionate about giving women unbiased advice on their personal finances, she is also keeping her eye on earning money to repay her investors.


And that’s where LearnVest’s latest product, the online bootcamps, come in. The three-week programs consist of daily emails with information and easy to do items that take minutes, according to von Tobel.  The investing bootcamp is LearnVest’s first paid offering, costing users $7.99.


“It’s cheaper than ‘Personal Finance for Dummies’ and easier to understand and accomplish,” von Tobel said. “We don’t want users to be overwhelmed.”


LearnVest’s content also provides affiliate marketing opportunities for the New York startup, where LearnVest earns money by suggesting personal finance products like credit cards.


Besides affiliate fees, LearnVest also sells advertising, in the hope that financial services firms and other brand advertisers will pay a premium for female users taking advantage of LearnVest’s educational content over what they’d pay for such users on general-interest websites.


Next Story: Your mobile app is spying on you Previous Story: Dark Roast Media integrates Publishers Clearing House sweepstakes into its social game


penis extender

MABUHAY ALLIANCE HOST THE 6TH ANNUAL ECONOMIC DEVELOPMENT CONFERENCE by mabuhayalliance


Large animal medicine takes a different tack. These animals are used for industry -- food production, breeding farms, racing, and so on. (The lines are blurred in some cases, such as horses that are really pets, and greyhounds used for racing.) "The client" here is the manager, producer, or trainer, while the "patient" is the dairy herd, the swine operation, or the overall breeding potential of a winning stallion. While humane treatment is an important factor, the goals are maximizing performance, productivity, and profit. Large animal medicine focuses on designing a Herd Health Program, where the outcome of an individual case takes a backseat to the cost and benefit for the overall group.

LearnVest founder and CEO Alexa von Tobel turned down Harvard and a life on Wall Street to make personal finance education accessible to women, and she has no intention of failing.


She thinks learning how to manage your money should be simpler, a passionate belief which comes from her personal need for her New York-based company’s product, a series of online tutorials on personal finance which have led some to dub her “Suze Orman 2.0.” On Tuesday, LearnVest announced the launch of three new on-demand, online Bootcamps covering basic personal finance, cutting costs, and investing. These products are just the latest iteration in von Tobel’s quest.


The 26-year-old von Tobel got the idea for LearnVest while working at Morgan Stanley, realizing that she had no idea how to manage her own finances.


“Here I was responsible for millions and millions of dollars and I didn’t know the first thing about getting a credit card or insurance,” von Tobel said. “I needed tools like these.”


Instead of attending Harvard Business School, von Tobel put all the money she’d earned after college into building LearnVest. Since then, the company has raised over $5.5 million in financing, most recently closing a $4.5 million round led by Accel Partners in April.


The LearnVest  CEO has been spending a great deal of time in the media spotlight recently. She was recently named to Inc.’s 30 Under 30 list of young entrepreneurs and has received media coverage from a number of local and national outlets including BusinessWeek and the New York Times. The ‘Suze Orman 2.0’ moniker first came from a Fox reporter.


But behind the media attention that even has the attractive blonde’s coworkers teasingly calling her ‘Finance Barbie’ is an entrepreneur possessed. Her self-deprecating humor and amiable demeanor are genuine, but von Tobel is shrewedly packaging herself and LearnVest as an accessible and fun medium for learning about personal finance. And she’s doing it from a cubicle alongside her employees in Learnvest’s cozy New York office.


Usage statistics suggest it’s beginning to work, with Learnvest receiving about 360,000 unique visitors in the U.S. per month according to Quantcast, a Web-traffic-measurement service..


While von Tobel is certainly passionate about giving women unbiased advice on their personal finances, she is also keeping her eye on earning money to repay her investors.


And that’s where LearnVest’s latest product, the online bootcamps, come in. The three-week programs consist of daily emails with information and easy to do items that take minutes, according to von Tobel.  The investing bootcamp is LearnVest’s first paid offering, costing users $7.99.


“It’s cheaper than ‘Personal Finance for Dummies’ and easier to understand and accomplish,” von Tobel said. “We don’t want users to be overwhelmed.”


LearnVest’s content also provides affiliate marketing opportunities for the New York startup, where LearnVest earns money by suggesting personal finance products like credit cards.


Besides affiliate fees, LearnVest also sells advertising, in the hope that financial services firms and other brand advertisers will pay a premium for female users taking advantage of LearnVest’s educational content over what they’d pay for such users on general-interest websites.


Next Story: Your mobile app is spying on you Previous Story: Dark Roast Media integrates Publishers Clearing House sweepstakes into its social game


online stock trading online stock trading how to lose weight fast

Business <b>News</b> You Need Today: Aug. 6, 2010 - DailyFinance

David Schepp has covered business news for more than a decade at news organizations such as Dow Jones, BBC News and Gannett. His beats have included technology, biotechnology, health care and workplace. He lives in New York's Hudson ...

What We&#39;re Reading: Motorcycle <b>News</b> - Wheels Blog - NYTimes.com

Valentino Rossi will join Ducati -- for real. And other motorcycle news we've been reading on the Web.

Next OpFlash &quot;takes on board feedback&quot; <b>News</b> - Page 1 | Eurogamer.net

Read our news of Next OpFlash. ... Latest News. Next Operation Flashpoint named . Latest Screenshots. Screenshot Today 09:40 . Developer EA DICE. Publisher Electronic Arts. Release Date TBC ...


MABUHAY ALLIANCE HOST THE 6TH ANNUAL ECONOMIC DEVELOPMENT CONFERENCE by mabuhayalliance


big white booty


Thursday, August 5, 2010

how to manage personal finances


LearnVest founder and CEO Alexa von Tobel turned down Harvard and a life on Wall Street to make personal finance education accessible to women, and she has no intention of failing.


She thinks learning how to manage your money should be simpler, a passionate belief which comes from her personal need for her New York-based company’s product, a series of online tutorials on personal finance which have led some to dub her “Suze Orman 2.0.” On Tuesday, LearnVest announced the launch of three new on-demand, online Bootcamps covering basic personal finance, cutting costs, and investing. These products are just the latest iteration in von Tobel’s quest.


The 26-year-old von Tobel got the idea for LearnVest while working at Morgan Stanley, realizing that she had no idea how to manage her own finances.


“Here I was responsible for millions and millions of dollars and I didn’t know the first thing about getting a credit card or insurance,” von Tobel said. “I needed tools like these.”


Instead of attending Harvard Business School, von Tobel put all the money she’d earned after college into building LearnVest. Since then, the company has raised over $5.5 million in financing, most recently closing a $4.5 million round led by Accel Partners in April.


The LearnVest  CEO has been spending a great deal of time in the media spotlight recently. She was recently named to Inc.’s 30 Under 30 list of young entrepreneurs and has received media coverage from a number of local and national outlets including BusinessWeek and the New York Times. The ‘Suze Orman 2.0’ moniker first came from a Fox reporter.


But behind the media attention that even has the attractive blonde’s coworkers teasingly calling her ‘Finance Barbie’ is an entrepreneur possessed. Her self-deprecating humor and amiable demeanor are genuine, but von Tobel is shrewedly packaging herself and LearnVest as an accessible and fun medium for learning about personal finance. And she’s doing it from a cubicle alongside her employees in Learnvest’s cozy New York office.


Usage statistics suggest it’s beginning to work, with Learnvest receiving about 360,000 unique visitors in the U.S. per month according to Quantcast, a Web-traffic-measurement service..


While von Tobel is certainly passionate about giving women unbiased advice on their personal finances, she is also keeping her eye on earning money to repay her investors.


And that’s where LearnVest’s latest product, the online bootcamps, come in. The three-week programs consist of daily emails with information and easy to do items that take minutes, according to von Tobel.  The investing bootcamp is LearnVest’s first paid offering, costing users $7.99.


“It’s cheaper than ‘Personal Finance for Dummies’ and easier to understand and accomplish,” von Tobel said. “We don’t want users to be overwhelmed.”


LearnVest’s content also provides affiliate marketing opportunities for the New York startup, where LearnVest earns money by suggesting personal finance products like credit cards.


Besides affiliate fees, LearnVest also sells advertising, in the hope that financial services firms and other brand advertisers will pay a premium for female users taking advantage of LearnVest’s educational content over what they’d pay for such users on general-interest websites.


Next Story: Your mobile app is spying on you Previous Story: Dark Roast Media integrates Publishers Clearing House sweepstakes into its social game


Large animal medicine takes a different tack. These animals are used for industry -- food production, breeding farms, racing, and so on. (The lines are blurred in some cases, such as horses that are really pets, and greyhounds used for racing.) "The client" here is the manager, producer, or trainer, while the "patient" is the dairy herd, the swine operation, or the overall breeding potential of a winning stallion. While humane treatment is an important factor, the goals are maximizing performance, productivity, and profit. Large animal medicine focuses on designing a Herd Health Program, where the outcome of an individual case takes a backseat to the cost and benefit for the overall group.
penis extender

MABUHAY ALLIANCE HOST THE 6TH ANNUAL ECONOMIC DEVELOPMENT CONFERENCE by mabuhayalliance


Friday, July 30, 2010

personal finance


penis enlargement

Jennifer Lopez signs deal to become new &#39;American Idol&#39; judge <b>...</b>

Jennifer Lopez has inked a deal to join American Idol's judging panel for its upcoming 10th season, an industry source tells People. The news dropped j...

Small <b>News</b> - Gadgetwise Blog - NYTimes.com

SanDisk has a new flash drive that's the size of a paper clip.

Political operatives on Journolist worked to shape <b>news</b> coverage <b>...</b>

Political operatives on Journolist discuss laying the 'analytical framework within the media elite' in order to shape news coverage.


2020Green by Second Story


internet marketing course

Jennifer Lopez signs deal to become new &#39;American Idol&#39; judge <b>...</b>

Jennifer Lopez has inked a deal to join American Idol's judging panel for its upcoming 10th season, an industry source tells People. The news dropped j...

Small <b>News</b> - Gadgetwise Blog - NYTimes.com

SanDisk has a new flash drive that's the size of a paper clip.

Political operatives on Journolist worked to shape <b>news</b> coverage <b>...</b>

Political operatives on Journolist discuss laying the 'analytical framework within the media elite' in order to shape news coverage.


big white booty

2020Green by Second Story


Thursday, July 22, 2010

personal finance planning

Web technology has revolutionized finance by making it easier than ever to monitor cash flow and track trends in your spending. Mint.com has been a leader in this realm for personal finance: its technology helps you track multiple accounts, analyze spending trends, and manage financial goals.

There isn’t a clear counterpart to class='blippr-nobr'>Mintclass="blippr-nobr">Mint for businesses, though. That’s where inDinero, a Y-Combinator-funded startup, comes in.

inDinero, which launches today, is a web-based financial dashboard for small businesses. Like Mint, it aggregates financial data from bank accounts, investments, and other sources and places them in a simple, easy-to-navigate interface where you can quickly see your income, spending, recent activity, and your financial runway.

The app is divided into five parts: Dashboard, Income, Spending, Planning and Trends. Dashboard provides an overview of your business finances, Income provides detailed information about your income streams, Spending breaks down your different costs, Planning helps you set goals for your business, and Trends analyzes and graphs out spending and income trends in order to provide useful insights.

Businesses need this type of information in order to minimize costs while maximizing revenues. While solutions such as Mint also aggregate financial information and analyze it, they are not focused on small businesses. We look forward to seeing inDinero’s business toolset grow and evolve.

Image courtesy of iStockphotoclass="blippr-nobr">iStockphoto, jwohlfeil

For more Business coverage:

    class="f-el">class="cov-twit">Follow Mashable Businessclass="s-el">class="cov-rss">Subscribe to the Business channelclass="f-el">class="cov-fb">Become a Fan on Facebookclass="s-el">class="cov-apple">Download our free apps for iPhone and iPad

Normally when people sign payment plans with a bank, they are not able to calculate the final costs themselves. This is mostly because they do not know how to factor in everything and how to derive the final charges. Thankfully they can use the services of a wonderful tool name CalcMoolator.


CalcMoolator is a website that offers a collection of free financial calculators online. You can use the site to compute payments involving vehicles, mortgages, jobs, taxes, money saving schemes, loans, credit cards, and anything else.


Each type of calculator has different values you input to reach your result. For instance the “Mortgage Payment Estimate Calculator” requires you to enter values of principal amount, interest rate (in percentage), duration of plan (in years), home value, annual taxes, annual insurance, and annual PMI. It factors in all these values and reaches the required mortgage amount.


Similarly other calculators on the site help people conduct financial calculations without having to learn any mathematical formulas.


Features:


  • A collection of free online financial calculator.

  • Each calculator factors in a number of values to reach a reasonably accurate result.

  • No extensive knowledge of banking or financial formulas is required.

  • Can be extrememly helpful for anybody planning to sign up a payment deal with a bank.

  • The website also has an iPhone app that Apple device owners can use.

  • Similar tools:  Mookal, MyBankTracker, IRS Withholding Calculator, WhatsTheCost, TripLittle and Repayment Calculator.


Check out CalcMoolator @ www.calcmoolator.com (by MOin from ThumbPress)


penis enlargement

Shepard Smith Unloads On Fox <b>News</b>, White House Over Shirley <b>...</b>

Shep Smith laid into his own network Wednesday, calling out Fox News for its role in hyping the Shirley Sherrod story based on an edited videotape (h/t Mediaite). Smith's critique began when he cut into Wednesday's briefing by White ...

Website users give BBC <b>News</b> redesign grief (and anger, and <b>...</b>

Josh Halliday: The BBC News website aims to engage with its users – who are leaving thousands of complaints – as its new look beds in.

EXCLUSIVE: Brad Pitt To Star In &#39;World War Z,&#39; Paramount Options <b>...</b>

While chatting up "World War Z" author Max Brooks at the booth for comic publisher Avatar Press, the writer confirmed to MTV News that the adaption of his novel about the zombie apocalypse is not only moving forward, but Brad Pitt is ...


Attentive participants by Julia Delligatti


internet marketing course

Shepard Smith Unloads On Fox <b>News</b>, White House Over Shirley <b>...</b>

Shep Smith laid into his own network Wednesday, calling out Fox News for its role in hyping the Shirley Sherrod story based on an edited videotape (h/t Mediaite). Smith's critique began when he cut into Wednesday's briefing by White ...

Website users give BBC <b>News</b> redesign grief (and anger, and <b>...</b>

Josh Halliday: The BBC News website aims to engage with its users – who are leaving thousands of complaints – as its new look beds in.

EXCLUSIVE: Brad Pitt To Star In &#39;World War Z,&#39; Paramount Options <b>...</b>

While chatting up "World War Z" author Max Brooks at the booth for comic publisher Avatar Press, the writer confirmed to MTV News that the adaption of his novel about the zombie apocalypse is not only moving forward, but Brad Pitt is ...


big white booty

Attentive participants by Julia Delligatti


Wednesday, July 21, 2010

personal finance blog


International scam artists defraud Americans out of more than $1 billion every year, according to the Federal Trade Commission (FTC).


The FTC warns that global con artists are adept at reaching out across national borders via phone, email, snail mail, and web sites to trick unsuspecting victims into sending cash or revealing personal financial information.


To help combat this problem, the nation's consumer protection agency has compiled a list of useful tips for avoiding overseas scams, Putting a Lid on International Scams: 10 Tips for Being a Canny Consumer, which include the following:


  • Don't respond to messages that ask for your personal or financial information, whether the message comes as an email, a phone call, a text message, or an ad. Don't click on links in the message, or call unfamiliar phone numbers left on your answering machine, either. The crooks behind these messages are trying to trick you into giving up your personal information. If you get a message and are concerned about your account status, call the number on your credit or debit card - or your statement - and check it out.


  • Don't play a foreign lottery. First, it's easy to be tempted by messages that boast enticing odds, or claims you've already won. Inevitably, you'll be asked to pay "taxes," "fees," or "customs duties" to collect your prize. If you send money, you won't get it back, regardless of the promises. Second, it's illegal to play foreign lotteries.


  • In the wake of a natural disaster or another crisis, give to established charities rather than one that seems to have sprung up overnight. Pop-up charities probably don't have the infrastructure to get help to the affected areas or people, and they could be collecting the money to finance illegal activity. Check out ftc.gov/charityfraud to learn more.


  • Don't send money to someone you don't know. That includes an online merchant you've never heard of -- or an online love interest who asks for money or favors. It's best to do business with sites you know and trust. If you buy items through an online auction, consider a payment option that provides protection, such as a credit card. Don't send cash or use a wire transfer service.


  • Don't agree to deposit a check from someone you don't know and then wire money back, no matter how convincing the story. By law, banks must make funds from deposited checks available within days, but uncovering a fake check can take weeks. You are responsible for the checks you deposit. When a check turns out to be a fake, it's you who is responsible for paying back the bank.


The tip sheet is available on the FTC Web site.

J.D.’s equation is correct, but it’s only part of the story. cash flow is in fact income minus expenses like the article states. However, cash flow does not correlate directly to wealth. You would naively think that wealth is the integral of cash flow with respect to time. It isn’t.


Suppose you earn $50,000. You immediately spend this money on building supplies and build a house with it. Your net cash flow is $0, but you now have a house that’s worth more than what you paid for it. You’ve got a property with a value of, say, $60,000. This is investment. Certainly you needed some cash flow to start the investing process, but cash flow itself is not wealth. Also, you now have the ability to generate $60,000 new dollars in positive cash flow by selling the house you built, in which case you can invest in something new.


The average American household income is about $3,000/month, after taxes. If you spend *all* of that on living expenses, you will never save your $50,000 to build your house. If you manage to cut your living expenses by half, you can now save your $50k in about three years. However, if instead you were able to double your income, you could save your $50k in half that time. If you take this even further and double your income again (to $12k/month) you could save you $50k in only 6 months. However, if instead you cut your living expenses by half a second time (to $750/month) it would still take you 22 months to save $50k.


You quickly hit a point of diminishing returns with cutting expenses, where each additional percent cut from your budget buys you less and less. The opposite is true for increasing your income. There is absolutely no way to save $50k in less than 16 months on $3,000/month. However, if you’re making enough money, there’s no limit to how fast you can do it.


Here’s one more example that’s not so extreme:


Set a goal to save $250,000. Pretend you want to buy a house in cash.

Start off with the same $3,000/month salary.

Start with the same $3,000/month living expenses.


Scenario 1: Your living expenses never change, but each year, you manage to increase your income 7% over the previous year. This seems feasible, it’s not a “get rich quick” scheme, you can probably find some way to improve your performance in whatever business you’re in by about this much.


You save your $250,000 in a bit over 12 years. At the end of the 12 years, you make about $120k/year. This is definitely a good salary, but it’s not ridiculously, infeasibly high.


Scenario 2:

You keep the same salary every year, but cut your expenses by 7%.


You save your $250k in 17 years, which is significantly longer. You’re also living on $920/month at the end of this, which is probably infeasible in real life. You just can’t keep cutting and cutting and cutting to this degree.


Scenario 3:

You combine both 1 and 2, both increasing your income by 7% every year, and cutting expenses the same amount. You’d think this would make a huge difference, right?


You’ll save your $250k in 10 years. This is definitely an improvement over either one of the other scenarios, but it’s not nearly the same sort of improvement you see if you solely increase income instead of solely decreasing spending. It also requires you to live on $1500/month at the end, which is certainly a lot more feasible that $920, but you still may think that’s a bit low.


This whole calculation ignores inflation (meaning, your 7% raise per year is probably more like 10% in absolute terms). It also means that at the end, when I say you’re living on $920/month, that’s $920 dollars at 2010 value, not 2027 value.


This is essentially the same concept that J.D. likes to call ‘the power of compound interest’, except applied in a slightly different way.


One other note on this example: selling your ’stuff’ makes almost no difference here. Even assuming you had $10k worth of stuff to get rid of at the beginning of this, it only buys you a few extra months in any of these scenarios. This is because a single, one-time influx of $10k is small in a scenario that takes 10-17 years to play out. At the end of these scenarios, you’re saving in the ballpark of $2000-$5000 every month. The extra $10k just isn’t that big of a deal any more. Selling ’stuff’ can help you reduce debts and stop paying interest to other parties if you can do it all at once, but it really doesn’t help you build long-term savings very well.


I know the site is called “get rich slowly”, but I like to think that is meant to convey an idea of perseverance and the fact that “get rick quick” schemes don’t work. It’s not meant to imply you should go artificially slower than you have to, just because.


In short: ask for a raise every year, even if you don’t always get it. Don’t be afraid to take a job at a competing company if they’ll offer you a better salary (assuming the job is otherwise similar). You don’t need to start your own company to make a few more percent every year. Just be valuable in your industry, show that to your employers, and don’t be afraid to ask for raises.


online stock trading

Journolister who bashed Fox <b>News</b> is on board that determines who <b>...</b>

Journolister Michael Scherer, who compared Fox News to a tribal organization, is on the board that will determine who gets the front row seat in the White House briefing room.

Dave Barry&#39;s Blog: BUSINESS <b>NEWS</b>

BUSINESS NEWS. This just in. (Thanks to Jeff Kleinman). Posted by Dave on July 21, 2010 at 09:33 AM | Permalink. Comments. Feed You can follow this conversation by subscribing to the comment feed for this post. ...

ASUS EP101TC Now Shipping with Android | Netbooknews - Netbooks <b>...</b>

Today the Netbook News team went down to the ASUS headquarters to hang out with the Eee Pad team, and we learned something that actually made us breath a sigh of relief. The EP101TC pad will dropping Windows CE and will be shipped with ...


Bankrate predicts what's on the personal financial horizon for 2008 by QuizzleTown


Tuesday, July 20, 2010

managing your personal finances

As you’ll read tomorrow (or Monday), I’ve entered a new phase in my life. After years of hard work and long hours building this blog (time that I’ve enjoyed), I’ve been shifting things around so that I have more free time. As a result, I’m going to have more time to devote to creating quality blog posts, instead of rushing around at the last minute looking for something to write about.


Because of this, it’s time yet again to take requests. I do this about once a year, and it’s a great way to get a feel for what GRS readers are interested in. I’d be grateful if you’d take the time to leave a comment below with topic suggestions or article requests. It doesn’t matter if we’ve covered the subject in the past. If you’d like me (or one of the other GRS staff) to write about it, let me know.


Have there been too many articles about credit cards? Too few articles about credit cards? Would you like to know more about individual savings accounts? Do you like the articles about the psychology of spending? Would it be helpful to have somebody come in to explain insurance concepts in plain English? Should I try to persuade my wife to share more of her recipes now and then? Let me know what you’d like to read about!


While you’re all providing feedback about the site, here are a few recent articles of note:


Over at The Simple Dollar, Trent and his readers had a thoughtful discussion about the obligations of wealth. “I think there is some inherent distrust of the rich in the mainstream of American society,” Trent writes as he describes how a wealthy person can keep from alienating his friends. There’s so much to say about this topic; I’m tempted to write an entire article about it.


GRS reader Steven writes a blog called Hundred Goals, which is about achieving your goals while managing your finances. After Sierra’s post this morning about travel, he dropped me a line to let me know that he has a recent article about how to have a great vacation.


Speaking of vacation, my pal Jason over at No Credit Needed spent time compiling day-use fees and free days for state parks across the United States. Handy page to bookmark!


And here’s more travel! At The Art of Non-Conformity, my good friend Chris Guillebeau has posted a beginner’s guide to travel hacking. I’ve been asking him to share this info for a long time; now I’ve got to take responsibility to use the knowledge he’s shared.


Finally, I’ve been giving a lot of interviews lately. I’m much more comfortable with these than I used to be. (They used to scare me to death!) Some examples:


  • Colleen from The Frisky interviewed me about how to save money even when you’re living paycheck to paycheck. This is a tough quandary, something I’m asked about a lot.


  • In an interview with BeFrugal, I discuss frugality, happiness, and conscious spending. (Note: “the ballot” should be “the balance” — I must have mumbled.)


  • Jeff Rose at Good Financial Cents also interviewed me. This interview is very much about the process of writing a book, which may or may not interest you.


  • I also spoke with Beverly Harzog from Card Ratings. We chatted about credit cards, of course, but also about other aspects of personal finance.


  • Finally, USA Weekend has a short piece on how to give your 401(k) a midyear check, for which author Richard Eisenberg interviewed me back in May. This is a perfect example of how much work goes into even a small newspaper article. Eisenberg spent 20-30 minutes on the phone with me, and I’m sure he did the same with the other folks he quotes. Plus, I’ll bet he spent a lot of time writing. I wouldn’t be surprised if there were 4-6 hours in this small piece.


Okay, one last thing before I go. Tim pointed me to a two-year-old New York Times series about the debt trap, which includes an interactive infographic showing average household debt loads over the past century.


That’s enough links for today. Please do leave a comment with topic requests or other feedback. Meanwhile, it’s time for me to go do some yardwork…


internet marketing course

There are always ways to make money, and it is possible to do this in any financial climate, however saving money, making it grow and making it work for you is another kettle of fish.

Below are just a few tips, ideas and ways as to how you can make the most out of your money and increase your personal wealth:

1. Set goals and objectives. To increase your personal wealth its best to know what you are starting off with and where you want to be in say 1 year, 3 years and 5 years.

2. Work out where your money is going. Total up how much income you bring in a month and work out where it all goes. Work out how much money you have spare or left over to play with which can be invested or saved.

3. Decide what will work for you and remember that there is no right or wrong, for example will creating a stocks and shares portfolio work, do you like a bit of risk? or will putting your money into fixed bonds and savings accounts be better for you if perhaps you like safe but steady growth.
TOP TIP: Before ploughing your hard earned money into anything do some market research, see how it has performed in the past, work out the risk and reward you could possibly get and so on.

4. Create a wealth plan/strategy. Decide what personal wealth figure you would like to achieve and then decide how you will do this and in what period of time. If you assign a period of time or deadline to something it will help it become more achievable and realistic. Within this wealth plan why not decide what short term and long term wealth creation strategies you might like to use and put in place?

5. Keep your eyes on the interest rates. Just because you have been with your bank since you were a child doesn't mean you have to stay with them until you are a pensioner. If there are better deals out there to be had then try and grab them with both hands.

REMEMBER: Always read any terms and conditions back to front and if possible get someone else to read through them as well. Don't tie your money up for long periods of time if you cannot afford to, and remember that high risk is just that. If you are not prepared to lose money as well as gain it then don't risk it, no matter how good the rewards may look.

I hope you have found this article both useful and helpful, I wish you every success in growing your money and increasing your personal wealth.


penis enlargement

Microsoft confirms Kinect price Xbox 360 <b>News</b> - Page 1 | Eurogamer.net

Read our Xbox 360 news of Microsoft confirms Kinect price.

Intel delivers cheaper six-core game chip | Nanotech - The <b>...</b>

Chip giant is shipping a less expensive six-core processor for the highest of high-end PCs. Read this blog post by Brooke Crothers on Nanotech - The Circuits Blog.

Haredim riot over &#39;obscene&#39; plasma screen <b>news</b> updates - Israel <b>...</b>

Jewish Scene: Some 25 Eda Haredit members protest outside postal branch in Bukharim neighborhood in Jerusalem, demanding Ynet news updates shown inside site's screens be removed. Two rioters who broke inside, hit security guards ...


how to lose weight fast